How to Save Money When You Live Paycheck to Paycheck
If there is nothing left at month's end, the usual advice does not help. A calmer way to save paycheck to paycheck, in amounts small enough to stick.
Most advice about saving quietly assumes you have spare money. “Just put away 20%.” But when you live paycheck to paycheck, there is no spare money at the end of the month, because the month always finds a way to use all of it. The standard advice does not just fail. It makes you feel like the problem is you.
It is not. More than half of people say they live this way, across several 2025 and 2026 surveys. You are not behind. You are normal. And there is a calmer way to save from here that does not require money you do not have.
The one change that matters: save first
The reason there is nothing left to save is that saving comes last, after the bills and the life and the small leaks. By the time you look, it is gone.
So flip the order. Save first, the day money arrives, before the month gets its hands on it. Move a small amount to savings the moment you are paid, and live on what is left. This is the single most powerful saving habit there is, and it works precisely because it does not rely on willpower or leftovers.
The catch most people add is making the amount too big. Do not. Start absurdly small.
Start smaller than feels worth it
Ten dollars. Five. Whatever amount is so small it does not change your month. The number is not the point yet. The habit is.
A tiny amount saved first, every single payday, does two things. It proves to you that you can save, which quietly rebuilds the belief that you are someone who saves. And it builds the muscle, so when a little more money does appear, the system to catch it already exists.
Once the small amount is automatic and you have not missed it, nudge it up a little. Slow is fine. Slow is how this lasts.
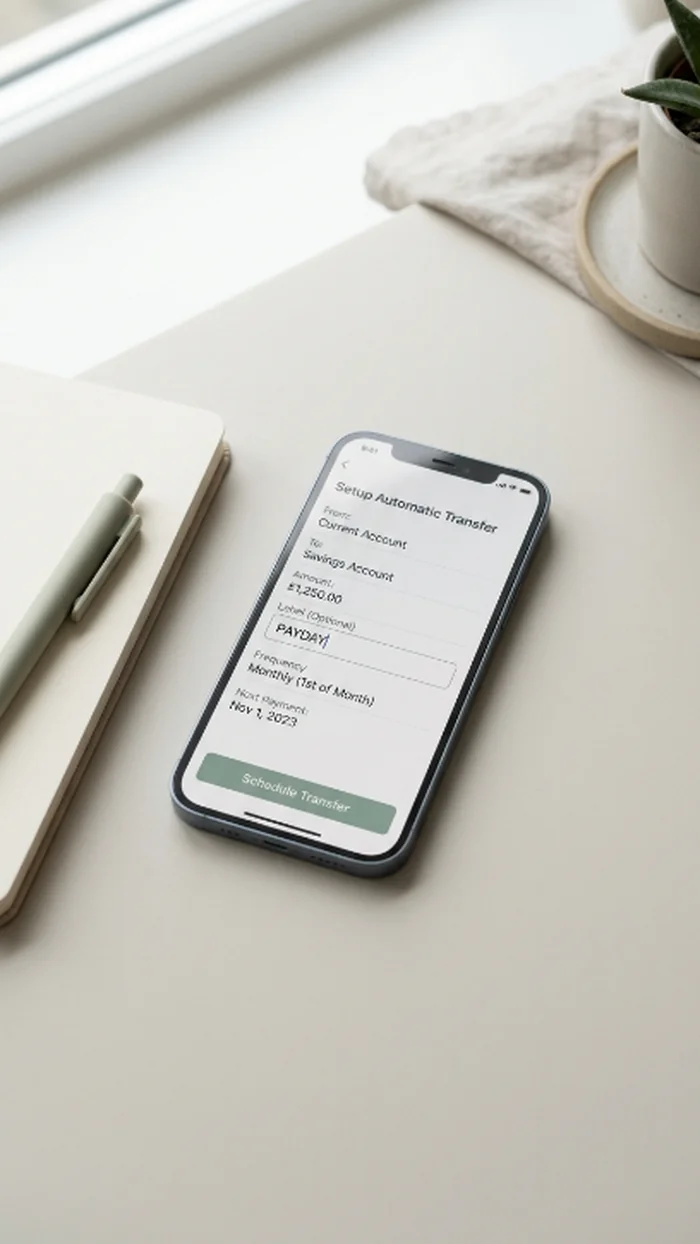
Save first, on payday, even if it is five dollars. A small amount saved every time beats a big amount saved never.
What starting small actually reaches
“Start smaller than feels worth it” is easy to dismiss, because $10 does not feel like saving. This is where each amount lands, saved every payday on a fortnightly schedule, with nothing added and no interest assumed.
| Per payday | After 6 months | After a year |
|---|---|---|
| $10 | $130 | $260 |
| $25 | $325 | $650 |
| $50 | $650 | $1,300 |
$10 a payday reaches $260 in a year. That is not an emergency fund, but it is the difference between a flat tyre going on a card and not. The number matters far less than the fact that it happens automatically, on the day you are paid, before anything else.
Then find some breathing room
Saving first works, but it works better with a little more room. The fastest way to find room is not more discipline, it is cutting a big fixed cost, which takes one effort and then pays you every month.
Two moves do the most here: cancel the subscriptions you forgot, and look at the big levers in how to save money fast. A renegotiated bill or a cancelled service frees up money with no ongoing willpower required, and that freed-up money can become your “save first” amount.
The honest part
Here is the truth gentler guides avoid. Sometimes the answer is not budgeting. It is income.
If you have cut what you reasonably can and the numbers still do not leave room to save, that is not a willpower failure. It is a math problem, and the lever is earning more, not trying harder. A small, sustainable side hustle or a raise can change the picture more than any saving trick. Saving habits matter, but they cannot create money that is not there, and pretending otherwise just adds shame to a hard situation.
So do both. Save first in tiny amounts to build the habit and the belief, and work on the income side in parallel. The habit will be ready when the money grows.
If you want to see where the tight spots actually are before changing anything, the free One- Month Money Reset Kit tracks one month without asking you to fix it yet.
How do you save money when you live paycheck to paycheck?
In amounts small enough to survive the month: $5-$10 moved automatically on payday, before spending starts. Then build one visible win — one subscription cancelled, one savings challenge completed — and let the proof that it is possible carry you to month two. The full step-by-step is in the sections above.
How can I save money fast on a tight income?
The fastest honest way is a 30-day burst: sell one thing, cut one recurring cost, and freeze one spending category for a month, then move the combined amount somewhere you cannot see it. Our how to save money fast ranks 21 ways by real impact, so you start with the levers that move the most money.
Frequently asked questions
How can I save money if I live paycheck to paycheck?
Save first, the day you are paid, before the month spends it, even if it is only a few dollars. Then free up room by cutting big fixed costs like subscriptions and bills. If there is still nothing spare after that, the real lever is increasing income.
How much should I save if I am on a low income?
Start with an amount so small it does not change your month, even $5 a payday. The goal at first is the habit, not the total. Once it is automatic, raise it slowly as you free up money or your income grows.
What should I do first if I have no savings at all?
Build a tiny starter fund of a few hundred dollars by saving first on every payday. Even $500 stops a small surprise from pushing you into debt. Once that exists, work toward a larger emergency fund.
Why do I have no money left at the end of the month?
Because saving and spending are happening in the wrong order. When saving comes last, the month uses everything first. Moving even a small amount to savings on payday, before you spend, fixes the order and quietly changes the result.
Is it worth saving small amounts?
Yes. Small amounts saved consistently build both the habit and the belief that you can save, and they create the system that catches more money when it appears. A small amount saved every payday beats a large amount you keep waiting to save.
Start this week
The next time you are paid, move a small amount to savings before you do anything else. Make it automatic if you can. Then pick one big bill to cut this month, and send that freed-up money the same way.
Free kit
Living paycheck to paycheck makes tracking feel harder than it should. The free One-Month Money Reset Kit gives you one simple month to get a clear picture.
Found this useful?
Pin it to come back to laterKeep reading
A few useful next steps
The 100 Envelope Challenge: How to Actually Save $5,050
The 100 envelope challenge saves $5,050 in 100 days. How it works, how much you save weekly, a lower-income version, and how to actually finish it.
The 52 Week Savings Challenge, Reworked for Real Pay
Save about $1,378 in a year, one deposit a week. How the 52 week challenge works, a friendlier version for real budgets, and how to finish it.
Cash Stuffing Without the Cash: Digital Envelopes That Actually Work
Cash stuffing for beginners without carrying cash: how digital envelopes work, the best categories to stuff, and when physical cash still helps.