Zero-Based Budgeting for People Who Hate Spreadsheets
Give every dollar a job until you reach zero. Zero-based budgeting in plain English, the honest catch, and a simpler way to actually keep it up.
Zero-based budgeting has a name that sounds like an accounting exam, which is a shame, because the idea behind it is one of the most useful in personal finance. Stripped of the jargon, it is just this: give every dollar a job before the month starts.
You do not need a spreadsheet or a finance degree to do it. You need one page and about half an hour. Here is how it works, the one catch to know about, and how to keep it up without it becoming a chore.
What zero-based budgeting actually means
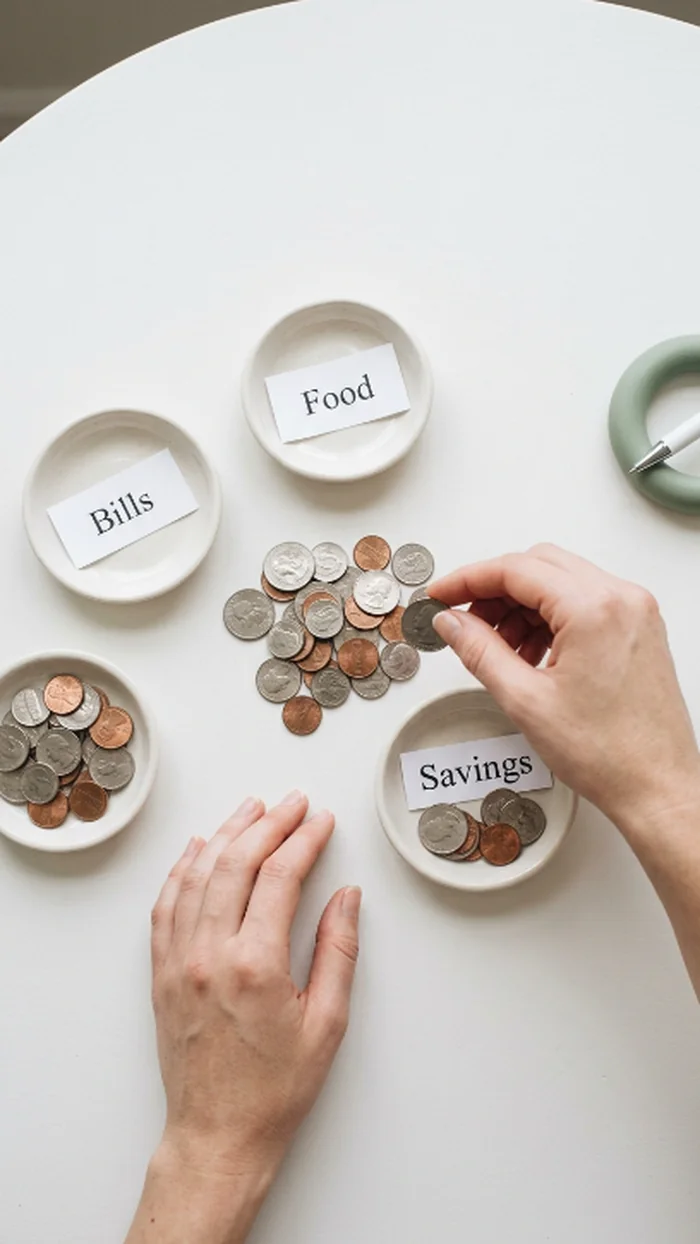
In a zero-based budget, you take your monthly income and assign every dollar to a specific job until you have nothing left unassigned. Income minus all your assignments equals zero.
That zero is the point. It does not mean you spend everything. Saving is a job. Debt payoff is a job. The emergency fund is a job. “Reaching zero” just means no dollar is left wandering around without a purpose, because the dollars without a purpose are the ones that quietly disappear.
Most budgets fail because money slips through the unassigned gaps. Zero-based budgeting closes the gaps. Every dollar is told where to go, so far less of it leaks.
How to do it on a single page
You can do this with a pen and one sheet of paper.
- Write down your income for the month. Your real take-home pay. If it varies, use last month’s actual income, as in budgeting on an irregular income.
- List every job that money has to do. Bills first, then food, transport, and the rest. Add savings and any debt payments beyond minimums as their own jobs.
- Assign dollars to each job until you hit zero. Subtract as you go. When you reach zero, every dollar has a home.
- If money is left over, give it a job too. Send it to savings, debt, or a sinking fund. Leftover money is just unassigned money waiting to vanish.
- If you run short, take from a lower-priority job. Trim fun or eating out until the math balances. That trade-off is the budget working, not failing.
Reaching zero does not mean spending everything. Saving is a job. It means no dollar is left without a purpose, because purposeless dollars are the ones that disappear.
A full zero-based month, worked through
Zero-based means every dollar gets assigned until nothing is unallocated. Here it is on $3,000 take-home.
| Job | Assigned | Running balance |
|---|---|---|
| Starting income | $3,000 | $3,000 |
| Rent | $1,050 | $1,950 |
| Utilities | $150 | $1,800 |
| Groceries | $380 | $1,420 |
| Transport | $140 | $1,280 |
| Debt minimums | $175 | $1,105 |
| Car repair fund | $75 | $1,030 |
| Christmas fund | $50 | $980 |
| Emergency fund | $250 | $730 |
| Eating out | $200 | $530 |
| Subscriptions | $45 | $485 |
| Personal spending | $300 | $185 |
| Buffer for the unplanned | $185 | $0 |
The last line is the one people skip, and it is the reason zero-based budgets usually fail. A budget assigned perfectly to zero with no buffer breaks the first time a bill lands $30 higher than expected. Assigning that leftover $185 to "the unplanned" is still zero-based, it just admits that months are not tidy.
The honest catch
Zero-based budgeting is powerful, but it asks more of you than a simple percentage rule. Because every dollar is assigned in advance, it only works if you check in regularly, usually weekly, to move money between jobs as real life happens. Skip the check-ins and the plan drifts out of date within a week.
That is the trade-off. More control, a little more upkeep. If even a weekly check-in feels like too much right now, the lighter 50/30/20 rule gives you most of the benefit for less effort, and you can graduate to zero-based later.
How to keep it up without hating it
The people who stick with zero-based budgeting keep it small and forgiving. Use broad categories, not thirty fiddly ones. Anchor the weekly check-in to a fixed moment, like Sunday evening or payday. And when you overspend a category, just move money from another job and carry on, the same forgiving reset that keeps any budget alive. The goal is a plan that bends, not one that breaks. If seeing each category’s limit matters more than the spreadsheet math, cash stuffing is the same idea made physical.
If a blank sheet is the part that stops you, the free One-Month Money Reset Kit gives every one of those jobs a line already waiting for it.
Frequently asked questions
What is zero-based budgeting?
It is a method where you assign every dollar of your income a specific job, savings and debt included, until you have nothing unassigned. Income minus all your assignments equals zero. It works because money without a purpose is the money that tends to disappear.
Does zero-based budgeting mean spending all my money?
No. Reaching zero means every dollar has a job, and saving, debt payoff, and your emergency fund are all jobs. You are assigning money, not spending it. A well-built zero-based budget directs a healthy share toward savings.
Is zero-based budgeting good for beginners?
It can be, but it asks for regular check-ins, usually weekly, to keep up to date. If that feels like a lot, start with the simpler 50/30/20 rule and move to zero-based once budgeting is a comfortable habit. The control is worth it once you are ready.
How is zero-based budgeting different from 50/30/20?
The 50/30/20 rule splits your money into three broad buckets and needs little upkeep. Zero-based budgeting assigns every individual dollar a job, giving you tighter control but requiring more frequent attention. One is simpler, the other is more precise.
How do I do a zero-based budget with an irregular income?
Budget last month’s actual income rather than guessing this month’s. Assign that known amount fully to its jobs, prioritizing essentials first. In strong months, the extra becomes savings or buffer jobs, smoothing out the lean ones.
Start this week
Take one sheet of paper. Write your income at the top, list the jobs that money has to do, and assign dollars until you hit zero. Then check in once this week and move money where real life needs it.
Free kit
If a blank page is intimidating, the free One-Month Money Reset Kit gives every dollar a place to land, no spreadsheet built from scratch required.
Found this useful?
Pin it to come back to laterKeep reading
A few useful next steps
The 50/30/20 Budget Rule, Explained Simply
The 50/30/20 budget rule explained with examples at three incomes: 50% needs, 30% wants, 20% savings. Calculate yours and adjust it when rent is high.
Best Budgeting Methods for Beginners: 5 Systems Compared
The best budgeting methods for beginners compared: 50/30/20, zero-based, pay yourself first, envelopes and the 80/20 rule. Who each suits, and what to skip.
How to Budget When Your Income Is Different Every Month
A calm budgeting method for freelance, commission, shift, or variable pay. Budget on last month's income, build a buffer month, and stop dreading slow ones.